The Ticker
Bull Market
The good ship Economy is sailing full-steam ahead with a stiff tailwind — sure, somebody just threw the captain overboard, but the engines are humming, the crew is busy, and the harbor lights ahead are shining bright.
Top Story
Nvidia CEO Jensen Huang Out as Board Acts on Spy Scandal
Nvidia's storied run under Jensen Huang came to a stunning halt this week as its board moved to remove the longtime CEO following a corporate investigation triggered by reports of extramarital affairs — one involving a woman suspected of espionage on behalf of China. CFO Colette Kress has been named interim chief executive as the company navigates one of the most dramatic leadership crises in Silicon Valley history, with Nvidia's earnings report still on the calendar for November 17.
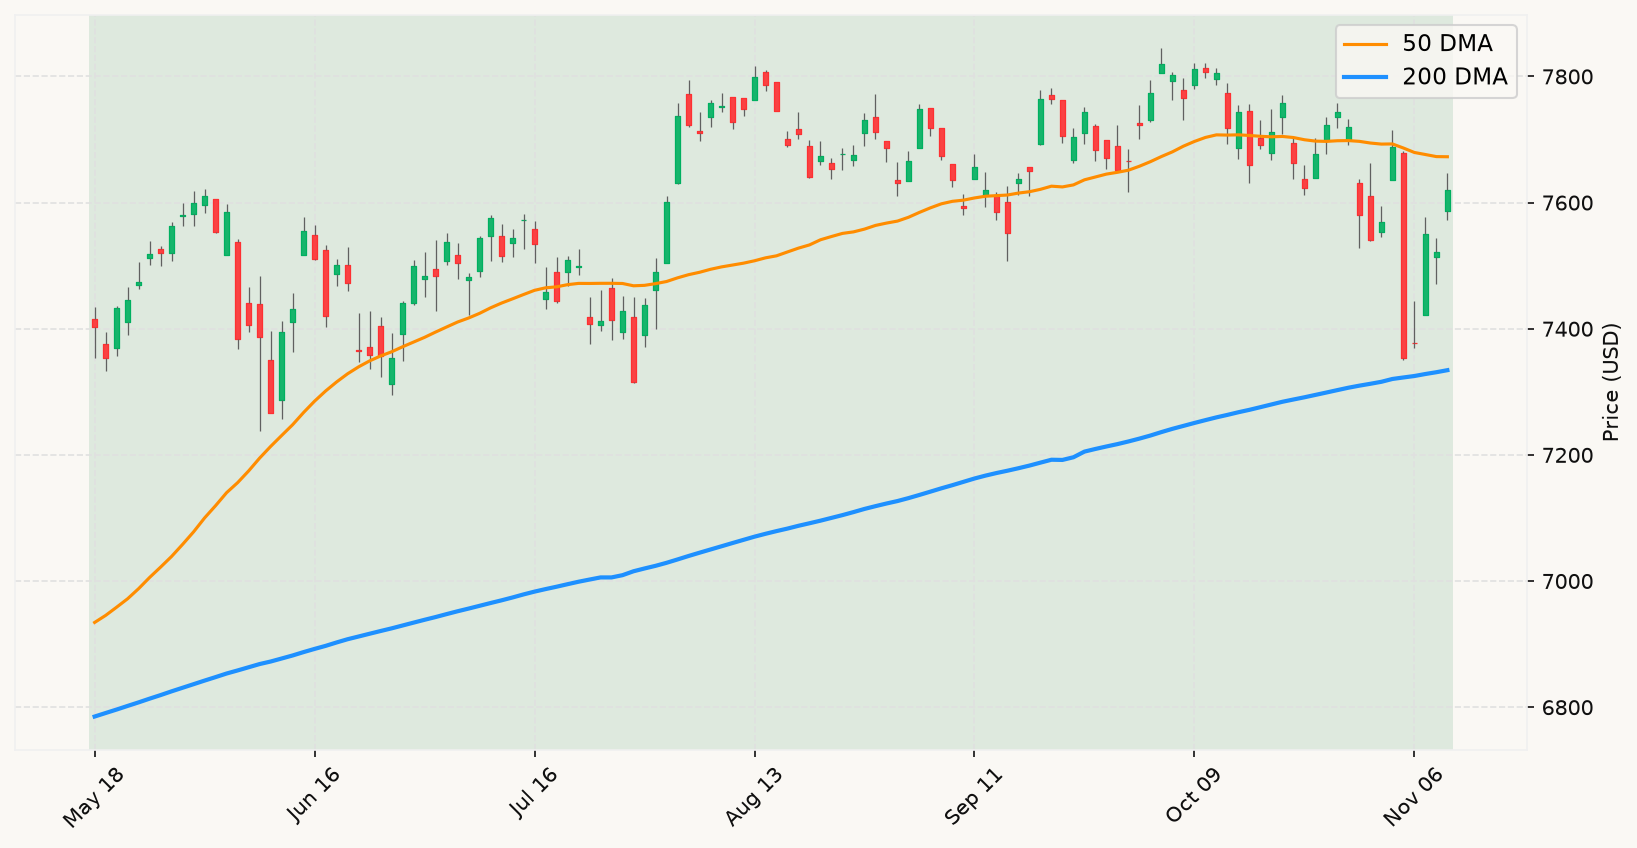
The Nvidia drama overshadows what has otherwise been a solid third-quarter earnings season. The S&P 500 has reclaimed ground from its early-November lows, with the broader market posting a strong rebound session Tuesday, led by tech. The neocloud sector had been a bright spot — CoreWeave delivered blowout quarterly results — but the Huang fallout quickly reversed those gains, pulling AI-adjacent names across the board lower in premarket Thursday.
The Fed policy picture sharpened considerably this week after Tuesday's October CPI print came in hotter than expected for the third consecutive month. Fed Governor Christopher Waller, speaking before the data dropped, explicitly floated a 50-basis-point December hike if core inflation held at 0.3% — and it did. Markets have now fully priced at least a quarter-point move at the December 9 FOMC meeting, with some participants betting on a larger half-point increase that would push the funds rate target range to 4.25–4.50%.
On the macro front, the dollar surged to its highest level since April 2025 as hawkish Fed repricing drove flows into the greenback, weighing on gold, which slipped below $4,000 an ounce for a third consecutive session. Saudi Arabia's surprise 26% jump in October oil production offered a partial offset to energy-price inflation pressures. And in a rare constructive note for the IPO market, Anthropic's offering was reported oversubscribed several times over ahead of a record $90 billion valuation listing — a signal that institutional appetite for AI infrastructure plays remains intact despite the turbulence surrounding the sector's most iconic figure. MoreLess
Six Month Chart (SPX)
⊞ Expand
The Ticker Analysis
Bull Trend Intact Despite the Nvidia Circus
The Nvidia CEO story is genuine headline shock, but the analytical question isn't whether the news is dramatic — it obviously is — it's whether it moves any needle that matters for how a long-term index investor should be positioned. The answer is no. Single-company governance crises, however spectacular, are company-specific events that the broader market digests quickly. The S&P 500 is still well above its primary market trend, the decline from the all-time high is a modest 2.5%, and there is zero velocity signature here consistent with the kind of grinding, broad-based deterioration that precedes a recessionary bear. This is noise wearing a very loud costume. Sector rotation out of semis and into defensive names may occur at the margin, but that's a tactical shuffle, not a structural signal.
The more consequential story today is the inflation and Fed policy combination. Three consecutive hot core CPI readings, a Fed governor openly floating a 50-basis-point December hike, and markets now fully pricing additional tightening — this is the genuine macro development worth tracking. Critically, though, the interest rate environment is not flashing the kind of distress that historically precedes equity bear markets. The 10-year/3-month spread is positive and widening, not inverted — which is the opposite of what preceded every modern recession. A Fed that is hiking into solid growth is a very different animal from a Fed that hiked into a slowdown. The former is uncomfortable for duration assets but historically has not derailed bull markets in equities. Employment conditions remain firm, with last week's jobs report coming in above expectations and no leading indicator of labor market deterioration currently in view.
The growth picture reinforces the bull case. Both real-time GDP tracking models are pointing to solid Q4 expansion, and the broader economic backdrop — strong consumer spending, resilient corporate investment — is not generating the kind of leading indicator convergence that the data historically requires before a recessionary bear becomes the base case. The 80% base rate for corrections resolving without becoming prolonged bears applies with full force here: the market has barely pulled back from its all-time high, we are nowhere near the sustained breach of the primary market trend that would raise the diagnostic alert level, and economic signals are pointing firmly in the wrong direction for a bear case to gain traction.
The Anthropic IPO oversubscription is worth noting as a sentiment indicator — institutional money is still chasing AI-related listings at scale despite the Nvidia turbulence, which suggests the smart-money read on the sector's fundamentals is not panicked. The correct posture here is unchanged: stay fully invested, treat the Nvidia CEO drama as the company-level event it is rather than a market-level signal, and watch the December Fed decision as a data point for the interest rate environment trajectory — not as a trigger for defensive repositioning. The primary market trend is intact, economic signals are healthy, and the base rates argue strongly against action. MoreLess