The Ticker Analysis
Stay the Course — The Noise Is Deafening, Not Dangerous
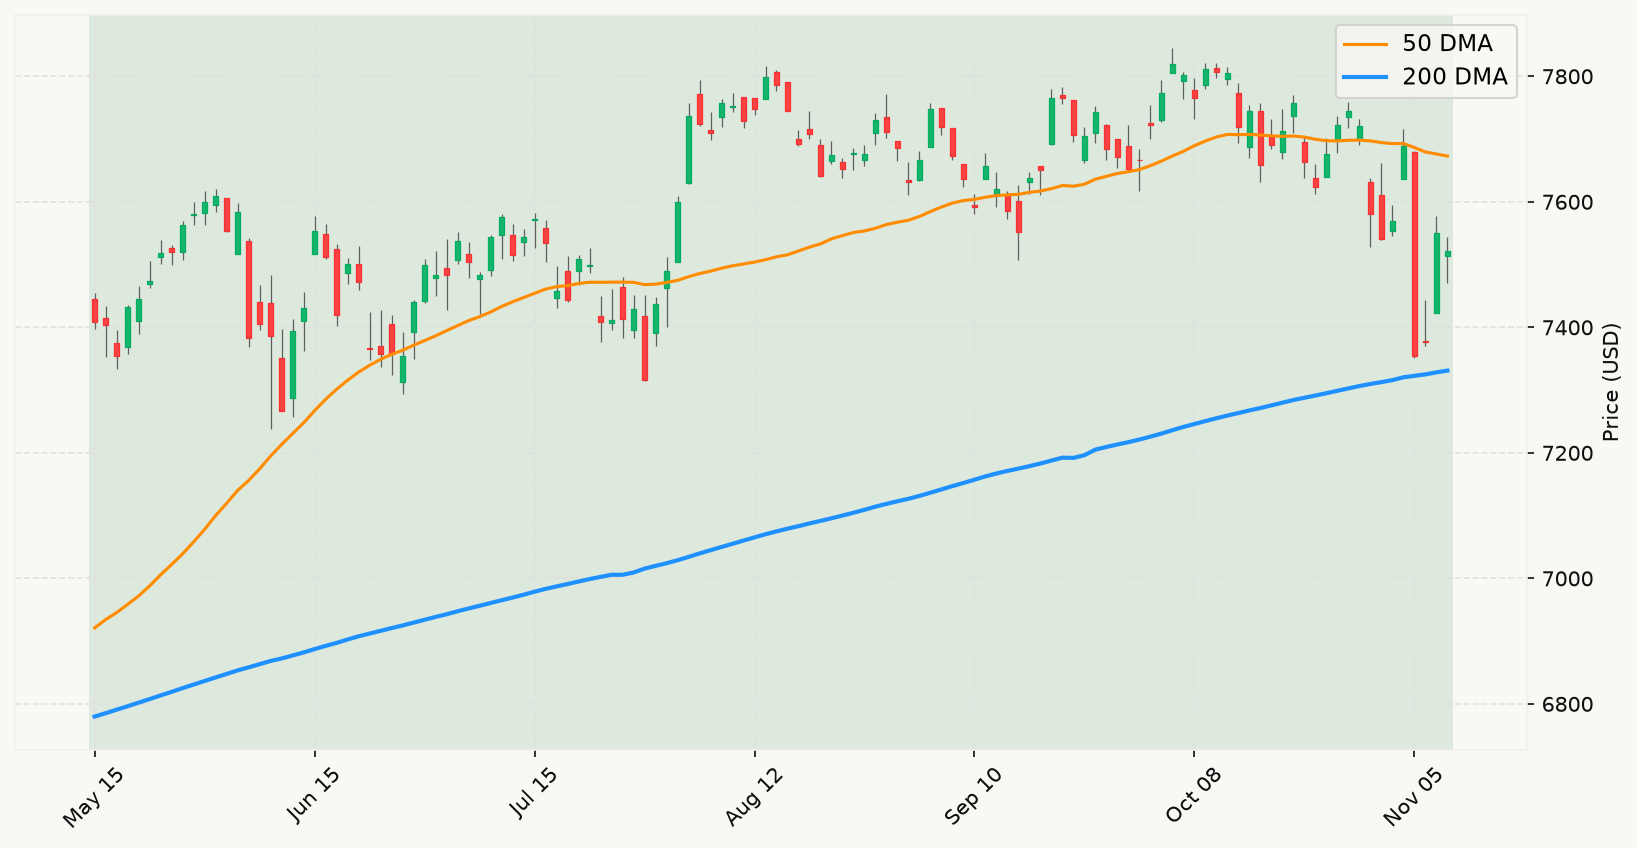
The primary market trend remains the most important fact on the table, and right now it is unambiguously bullish. The S&P 500 is trading comfortably above its long-term trend line, the interest rate environment has re-steepened into positive territory, employment conditions show no signs of the deterioration that has historically preceded recessionary bears, and the current drawdown from the all-time high is a modest single-digit pullback. None of the signals that have historically converged ahead of prolonged bear markets are present. That does not mean the headlines aren't noisy — they absolutely are — but noise is not signal, and conflating the two is how investors destroy long-term returns.
The Nvidia scandal is a vivid example of market noise wearing signal's clothing. A CEO governance crisis at a single company, however large, does not move any of the needles that actually matter: it doesn't change the primary trend, it doesn't alter the velocity profile of the current decline, and it doesn't push any leading economic indicator toward recession confirmation. The stock taking a hit is a price event, not a macro event. The fact that Nvidia is already bouncing this morning — with AI peers following — is exactly the kind of quick-reversal behavior you'd expect from sentiment-driven dislocations rather than fundamental repricing. Worth watching from the sidelines as a spectator; not worth repositioning over.
The hotter-than-expected CPI print and the resulting surge in December hike odds is the story that deserves more analytical weight, though even here the framework's verdict is clear: a data point that re-prices the Fed's near-term path is not, by itself, a recession signal. The interest rate environment shifted from inverted to positively sloped earlier this year — a meaningful improvement in monetary policy signals — and while a December hike would put modest additional pressure on the economy, the historical record shows that equity markets can absorb rate hikes robustly as long as growth is intact. With both growth nowcasts running well above stall speed, the economic backdrop does not support a defensive posture. The paradox of surging AI revenues easing financial conditions while the Fed simultaneously tightens is real, but paradoxes resolve — and they usually resolve in the direction the primary trend is already pointing.
The practical positioning answer here is straightforward: stay fully invested. The 80/20 base rate alone argues strongly against defensive action — historically, 80% of 10%+ declines resolved without becoming prolonged bears, and you haven't even seen a 10% decline from the recent high. Sentiment has pulled back (Bulls at 37%, Bears at 24% — the most pessimistic reading since April), which is actually a mild contrarian positive: excessive pessimism at a moment when the primary trend, the economic backdrop, and the interest rate environment are all constructive tends to precede gains, not losses. The AI earnings wave this week is re-igniting the sector that has led this bull market, and Iran-driven oil volatility, while worth monitoring, has not historically been a sufficient standalone catalyst to derail equity bull markets absent a broader economic deterioration. Hold your position, tune out the scandal headlines, and let the framework do its work. MoreLess