The Ticker
Bull Market
The sun is out, the barn door's wide open, and the bulls are practically doing backflips in the pasture — cheaper oil, a sturdy economy, and a tech sector on fire have this market feeling like a summer county fair, even if the Fed is lurking by the funnel cake stand with a clipboard.
Top Story
Hot CPI Seals December Rate Hike as Waller Eyes 50 Basis Points
Inflation refused to cooperate in October, with consumer prices rising faster than Wall Street expected and the core rate staying stubbornly elevated — leaving the Federal Reserve with little political cover to pause its tightening cycle before year-end.
The earnings picture remains a mixed but broadly constructive backdrop. TSMC's blowout October revenue — nearly six times its year-ago level — signals that AI-driven chip demand is powering through the geopolitical turbulence. Sanmina surged after crushing earnings expectations, and Take-Two rose on strong GTA VI preorder momentum, while names like JBS and On Running faced sharp post-earnings selloffs, underscoring that this is a market that is rewarding execution and punishing any whiff of a miss.
Fed Governor Waller came out swinging Tuesday, making clear that a December rate hike is essentially a done deal and explicitly putting a 50-basis-point move on the table if inflation remains uncooperative. With the hot CPI now in hand, the debate has shifted from whether the Fed hikes in December to whether it hikes by 25 or 50. Dallas Fed President Logan separately said the committee needs at least two more quarter-point increases — a signal that the Fed's tightening posture is broader than a single voice.
The macro wildcard on the positive side is oil. Brent's dramatic retreat from its late-October peak, driven by Trump's conciliatory signals on Iran and recovering OPEC output, is functioning as an effective tax cut for consumers and a potential inflation relief valve heading into year-end. How durable that relief proves to be — especially with Strait of Hormuz shipping risks still alive — will be a critical variable for both CPI prints and Fed deliberations in the weeks ahead. MoreLess
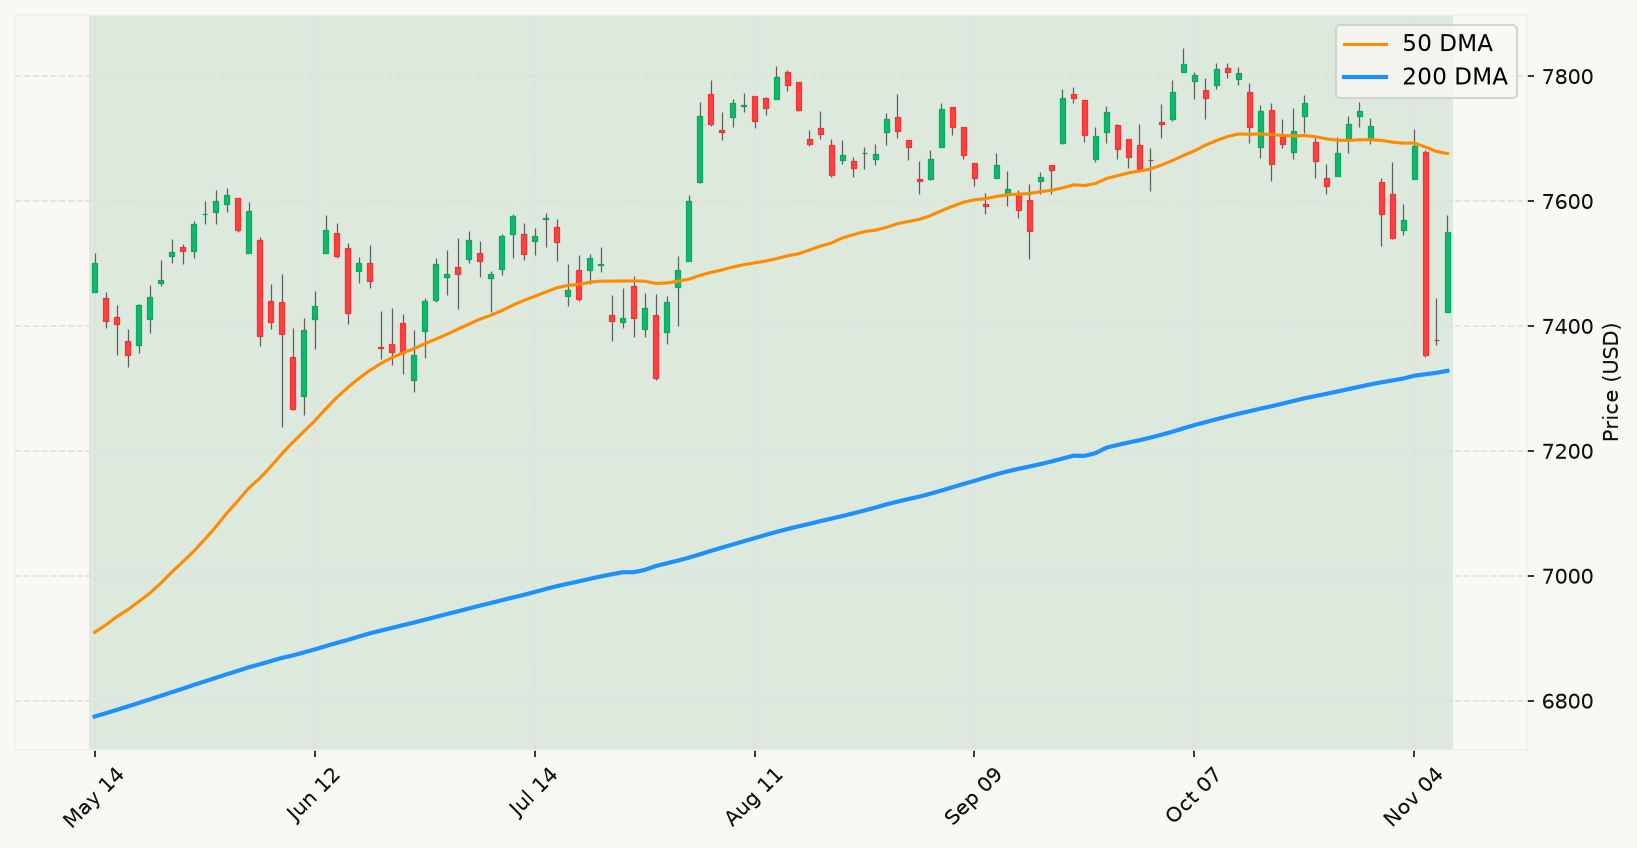
Six Month Chart (SPX)
⊞ Expand
The Ticker Analysis
Bull Market Intact — Stay the Course
Today's hot CPI print and Waller's half-point trial balloon are unambiguously noise from a positioning standpoint. The stock market is trading comfortably above its primary trend line, and the economy is expanding at a healthy pace — the leading indicators are simply not generating the recessionary convergence that would put a prolonged bear market on the table. The Fed tightening narrative is real, but it is a known and priced risk; the monetary policy signal has been bullish, with a positively-sloped rate spread offering no inversion warning. The market sold off on these inflation fears last week and has already recovered most of those losses. That behavior is exactly what you'd expect from a bull market shaking off a news-driven correction.
The Iran-driven oil collapse is legitimately significant macro news — but it cuts in a bullish direction. A roughly 22% decline in Brent from its October highs reduces one of the most credible near-term threats to both growth and inflation simultaneously. Lower energy costs act as a demand stimulus, ease core goods inflation passthrough, and reduce the probability that the Fed needs to deliver a shock-and-awe 50-basis-point hike. The market correctly front-ran this by rallying sharply on Monday. The oil move is the kind of exogenous positive shock that tends to give a bull market more runway, not less.
The Anthropic IPO roadshow is worth watching as a sentiment barometer, but it's noise for the broader market framework. What matters is not whether Anthropic prices at $70 or $78 — it's what TSMC's six-fold revenue surge tells us about underlying AI infrastructure demand. That is real economic activity, with real capex implications, and it supports the picture of an economy that is not rolling over. TSMC's numbers are confirming the bull case in semiconductors and, by extension, the broader tech sector that dominates index weighting.
The base case here is straightforward: the market remains in a bull trend, employment conditions are healthy, growth nowcasts are positive and rising, and the geopolitical tail risk that dominated October has begun unwinding. A 3.4% drawdown from the all-time high is a routine intra-year pullback — nowhere near the threshold where the diagnostic framework shifts to heightened vigilance. The correct posture is to stay fully invested. The only scenario that changes this assessment is a sustained, grinding decline that breaches the primary trend line to the downside — and that is not what the evidence shows today. MoreLess