The Ticker Analysis
Blue Wave & Oil Drop Confirm the Bull Case
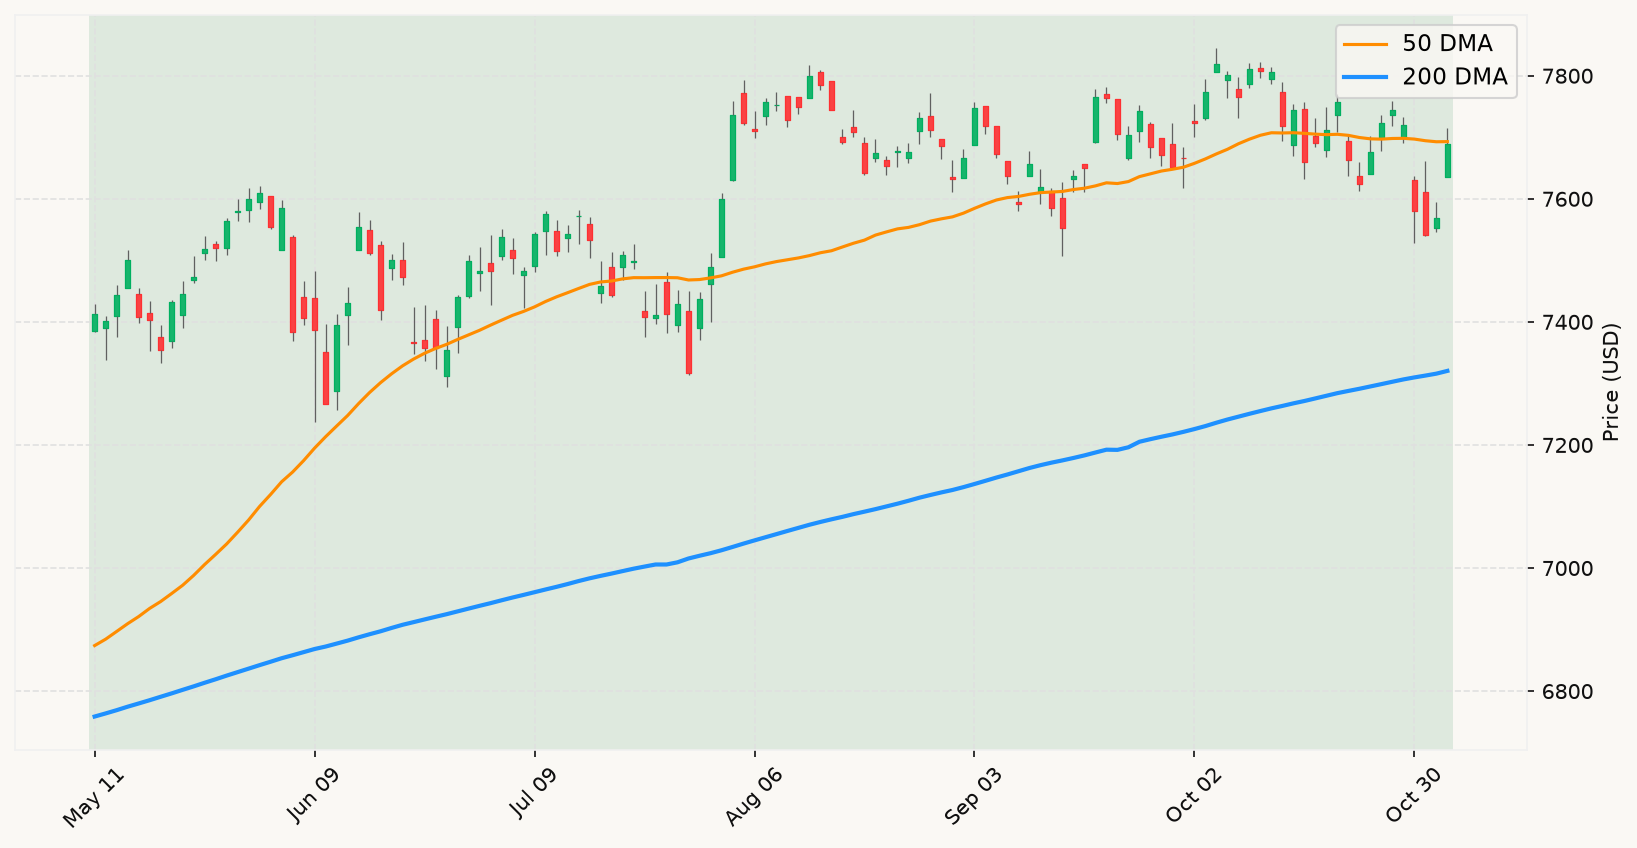
The midterm results delivered exactly the kind of decisive, unambiguous outcome that markets tend to embrace — not because divided government is inherently bullish, but because uncertainty is the market's true enemy and Tuesday's blue wave eliminated the ambiguity. The S&P 500 is sitting comfortably above its primary market trend, the drawdown from the all-time high is minimal, and the broad index is now posting one of its strongest post-midterm performances in four decades. By every structural measure the framework tracks, this is a bull market regime. The burden of proof falls squarely on the bear case, and right now that case has nothing credible to stand on.
The AI hardware/semiconductor selloff deserves a clear-eyed ruling: noise. Yes, the Democratic sweep raises the probability of data center regulation and may slow the AI infrastructure buildout at the margin. But the market is not collapsing — it's rotating. Megacap tech, healthcare, and consumer names are absorbing capital fleeing semiconductors. The primary trend remains intact and the velocity of any decline is nowhere near the thresholds that would trigger a diagnostic review. A sector rotation — even a sharp one — is emphatically not a signal. It is exactly the kind of dramatic, headline-generating event that the framework identifies as a distraction. The question that matters is whether the overall market's trend structure is breaking down. It is not.
The oil collapse is the most genuinely macro-consequential development of the week, and its implications cut clearly bullish. The Iran war has been the dominant source of stagflationary pressure globally for most of 2026 — a simultaneous hit to growth and inflation that complicated every central bank's calculus. A credible US-Iran diplomatic opening that takes crude below $95 per barrel changes that equation materially. It directly reduces input costs, eases the energy inflation component that has kept monetary policy signals tight, and improves real consumer purchasing power almost immediately. The interest rate environment is responding accordingly, with long-end yields retreating — a direct tailwind for equity valuations, particularly in rate-sensitive sectors that have been underperforming all year.
Employment conditions remain solid, the interest rate environment is shifting in a constructive direction, and growth nowcasts are firmly in expansion territory. The 80% base rate — the historical finding that the overwhelming majority of market pullbacks resolve without becoming prolonged bears — has never been more applicable than it is to the current 1.67% drawdown from the all-time high. The market is not even in correction territory. There is no velocity signal, no recession confirmation, and no convergence of deteriorating leading indicators. The posture prescribed by the data is unambiguous: stay fully invested, tune out the semiconductor drama, and let the oil-price tailwind and post-midterm clarity work in your favor. MoreLess