The Ticker Analysis
Bull Trend Intact — Political Drama Is Just Noise
The headline grabbing markets this morning — Democrats seizing both chambers of Congress — is exactly the kind of dramatic political news that feels like it demands an urgent portfolio response. It does not. Policy uncertainty, regulatory risk, gridlock fears, and shifting legislative agendas are perennial features of the market landscape. The historical record is unambiguous: political outcomes, however surprising, do not reliably move equity markets in a predictable direction over any meaningful time horizon. By the time the election results are digested, the market's real-time price mechanism has already begun absorbing the information. The dip-buying that immediately followed the futures selloff overnight is itself a data point — the market's initial gut reaction was quickly challenged by participants who saw value. The ruling on this headline: Noise.
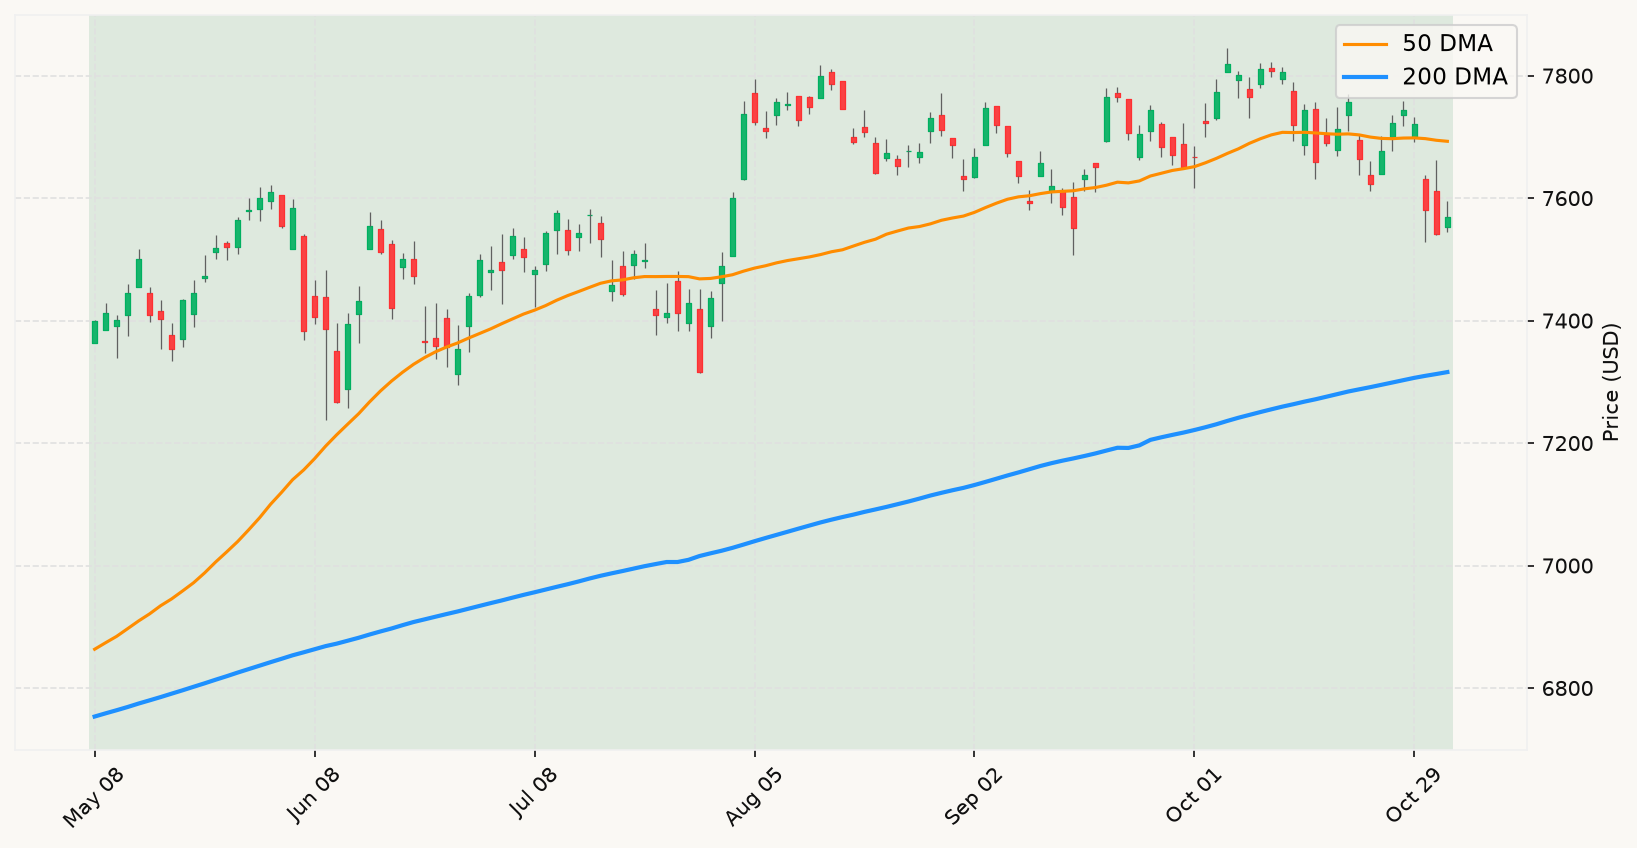
What actually matters from a signal standpoint is where the market stands structurally. The S&P 500 remains comfortably above its primary market trend line — the bull case is intact by that measure, and the burden of proof falls squarely on the bears. The current drawdown from the early-October all-time high is in the low single digits, well short of the 10% threshold that would even begin to register in the historical dataset of meaningful declines. At this stage of a pullback, the base rate is overwhelmingly favorable: the vast majority of episodes that feel like the beginning of something worse resolve quickly and completely. Patience, not positioning defensiveness, is what the data calls for. Meanwhile, AMD's blowout quarter — with Data Center revenue nearly doubling and Q4 guidance well above the Street — is a live confirmation that the AI capital expenditure cycle driving this bull market has not rolled over. That's the kind of fundamental backdrop that sustains primary trends, not disrupts them.
The interest rate environment sends no recession warning. The 10-year/3-month spread is solidly positive, with no inversion in sight — the monetary policy signal that has preceded every modern U.S. recession is simply absent. Employment conditions show no deterioration. Growth nowcasts for Q4 are running well above stall speed. The convergence of signals — a grinding equity decline plus simultaneous deterioration in leading economic indicators — that would justify a defensive posture is nowhere to be found. What we have instead is a healthy market taking a normal breather after reaching all-time highs, against a backdrop of solid growth, strong corporate earnings, and an actively easing geopolitical risk premium as Iran diplomacy advances. The CVS breakup story is a company-specific restructuring event and has no read-through for the broader market regime.
The Iran-diplomacy-driven oil price decline is worth watching as a potential macro tailwind, not a warning sign. If a durable ceasefire materializes, the disinflationary impulse from lower energy prices would give the Fed more flexibility and reduce one of the genuine headwinds to consumer spending. That would be a positive development for equities broadly, reinforcing rather than undermining the bull case. For now, the prescribed posture is straightforward: stay fully invested. All-time highs are historically associated with above-average forward returns, the primary market trend is unambiguously bullish, and none of the leading recession indicators have moved toward convergence. The noise level is high this morning, but the signal is calm. MoreLess