The Ticker
Bull Market
The economic engine is purring like a well-fed cat in a sunny window — bulls are strutting down Main Street, hats tipped, while the bears grumble in the alley and wait for a storm that just won't come.
Top Story
Marvell's $115 Billion AI Bet Reshapes Chip Industry in Blockbuster Deal
Marvell Technology kicked off November with a thunderclap, announcing a $115 billion all-stock deal to acquire optical components maker Lumentum Holdings — the largest tech merger of 2026 and one of the biggest corporate bets on the AI infrastructure build-out to date. The move signals that the race to own every layer of the AI data center stack is accelerating, even as investors grow increasingly nervous about whether the torrent of AI spending will ultimately pay off.
The Marvell-Lumentum deal lands in the middle of a consequential earnings season. Apple reports its fiscal fourth-quarter results today — the first under new CEO John Ternus, who took the reins from Tim Cook in September. Wall Street is watching closely for guidance on the critical Christmas quarter, clarity on AI strategy, and any color on how rising memory chip costs are hitting margins. With Apple shares up roughly 27% this year, the bar for the new chief executive is high from the opening bell.
The Federal Reserve held rates steady at its October meeting, but sent a clear message: December is live. Markets are pricing an approximately 86% probability of a quarter-point hike when the FOMC next convenes, reflecting persistent inflation pressures amplified by elevated energy prices tied to the ongoing Iran conflict. Fed Chair Kevin Warsh dismissed any suggestion that the pause was politically motivated, though the timing — days before midterm elections — drew inevitable scrutiny from observers on both sides.
Those midterm elections arrive Tuesday, and political uncertainty is layering an additional fog over markets already navigating rate anxiety and an AI trade that cracked hard in October. Polymarket odds point strongly toward Democrats reclaiming the House, and possibly the Senate, a shift that would reshape the legislative landscape heading into 2027. Meanwhile, the aftershocks of the record $6.3 billion Binance hack — attributed to North Korea-linked hackers — continue rippling through the crypto space, adding a geopolitical cybersecurity dimension to an already crowded risk calendar. MoreLess
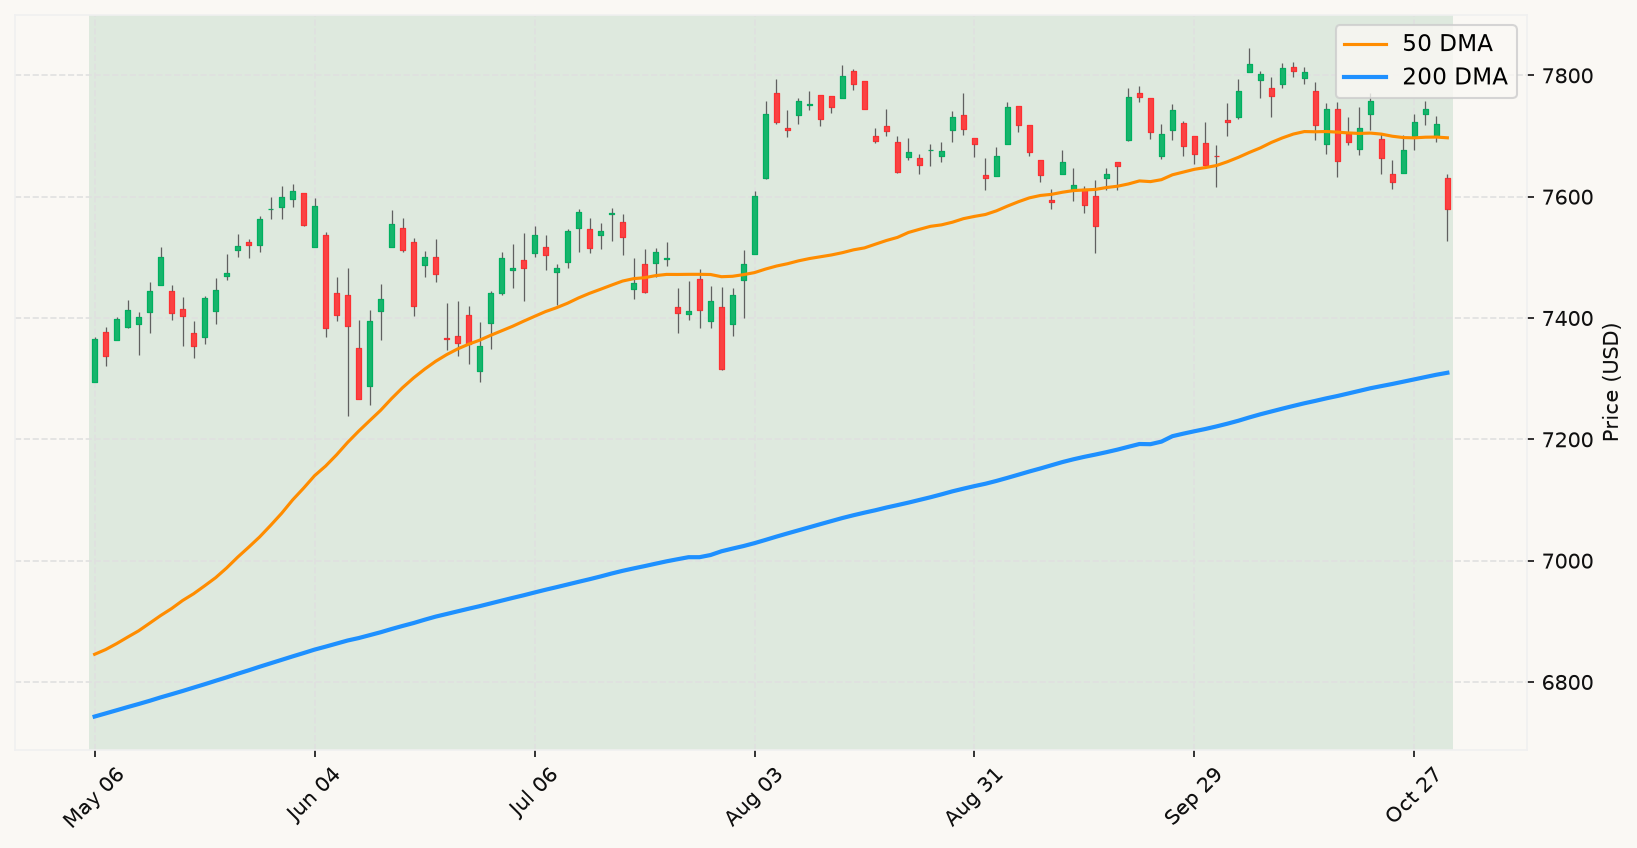
Six Month Chart (SPX)
⊞ Expand
The Ticker Analysis
Stay the Course — The Bull Trend Is Intact
The primary market trend remains solidly bullish — the S&P 500 is trading comfortably above its long-term trend line, and the current pullback from the October all-time high is in modest single-digit territory. From a historical base-rate standpoint, this is the regime where staying fully invested has consistently been the correct posture. Nothing in today's headlines — not the Marvell-Lumentum megadeal, not the Apple earnings test, not the midterm uncertainty — changes that assessment in any meaningful way. The market is doing what markets do: digesting a lot of noise simultaneously.
The Marvell-Lumentum deal is a signal worth reading correctly. A $115 billion all-stock bet on AI optical infrastructure isn't the behavior of a corporate sector that believes the growth story is ending. It is, if anything, the opposite — a confirmation that the largest players in the semiconductor supply chain are still competing aggressively for positioning in a multi-year capex cycle. The knee-jerk sell-off in Marvell shares on deal dilution concerns is a classic short-term reaction; the strategic logic of the transaction reflects the same durable AI demand thesis that has been driving this bull market. Oracle's concurrent $10 billion equity-and-debt raise fits the same pattern — companies raising capital at scale to fund infrastructure expansion. These are growth-cycle behaviors, not contraction signals.
The Fed backdrop deserves precise calibration. The rate environment has pivoted from cuts to hikes, and that is a genuine headwind for rate-sensitive multiples — particularly in the high-growth tech names that led the October selloff. But the interest rate environment here is not flashing recessionary warning signals. The spread between short and long rates has normalized into positive territory, GDP nowcasts are running solidly above 2.5% for Q4, employment conditions show no signs of deterioration, and the Fed is hiking into a strong economy, not a weakening one. The 1970s analogy some bears are reaching for requires a wholesale collapse in real growth that simply isn't visible in the leading data. A December hike is priced and expected — that's very different from a shock.
The midterm elections and the Binance hack are the clearest noise items on today's docket. Political outcomes historically have no durable directional effect on equity markets — the data across decades of election cycles is unambiguous on this point. As for the crypto heist: dramatic as it is, a hack of a cryptocurrency exchange does not touch any of the macro transmission channels that matter for the S&P 500's primary trend. Employment conditions are healthy, nowcasts are positive, the trend line is holding — the bear case remains without a confirmed second leg. The correct posture today is the same as it was last week: fully invested, patient, and tuned to the actual signals rather than the cacophony of headlines. MoreLess