The Ticker
Bull Market
The sun is shining on Wall Street's front porch — the economy's humming, the jobs market's holding its own, and the money weather is staying fair — so grab a lemonade and let the good times roll, even if the neighbor's dog (Alphabet) is barking up a storm next door.
Top Story
Alphabet Craters 10% as Google Search Miss Sparks AI Monetization Fears
Alphabet's stock tumbled more than 10% after reporting its first simultaneous earnings and revenue miss in nearly four years, rattling tech investors and reigniting debate about whether massive AI spending is paying off fast enough. Google Search revenue grew just 12% — well below the 17% growth posted just last quarter and shy of Wall Street's 15% target — raising fears that generative AI competitors are beginning to erode Google's dominant search franchise.
Earnings season is delivering a tale of two tapes. Microsoft's Azure cloud surged 48% and the company beat on revenue and earnings across the board, demonstrating that disciplined AI infrastructure spending can generate visible, bankable returns. But Alphabet's negative free cash flow and a nearly 30% EPS miss showed the other side of the coin — even companies with genuine AI capabilities are not immune to the scrutiny of the moment. ServiceNow and Fortinet added to the software sector pain, while Samsung's hardware miss kept semiconductor sentiment in check. The bar for "good enough" in AI has clearly risen.
The Federal Reserve delivered its own message Wednesday, holding rates steady in a 10-2 vote while two officials pressed for an immediate hike. Chair Warsh's press conference left December wide open, and markets wasted little time pricing in the likely next move — futures now imply roughly an 85% probability of a December hike. The Fed upgraded its characterization of economic activity from "solid" to "strong," signaling it sees no urgency to ease despite tight financial conditions.
On top of earnings and the Fed, today's Q3 GDP advance estimate came in at 3.4% annualized, beating the consensus of 3.2% and nearly doubling the 1.5% pace from Q2. That kind of growth print gives the Fed ample cover to follow through on December tightening. Meanwhile, diplomatic signals from Vice President Vance toward Iran offered modest relief in energy markets, with crude pulling back from elevated geopolitical highs — though oil remains a key wildcard for inflation and central bank patience heading into year-end. MoreLess
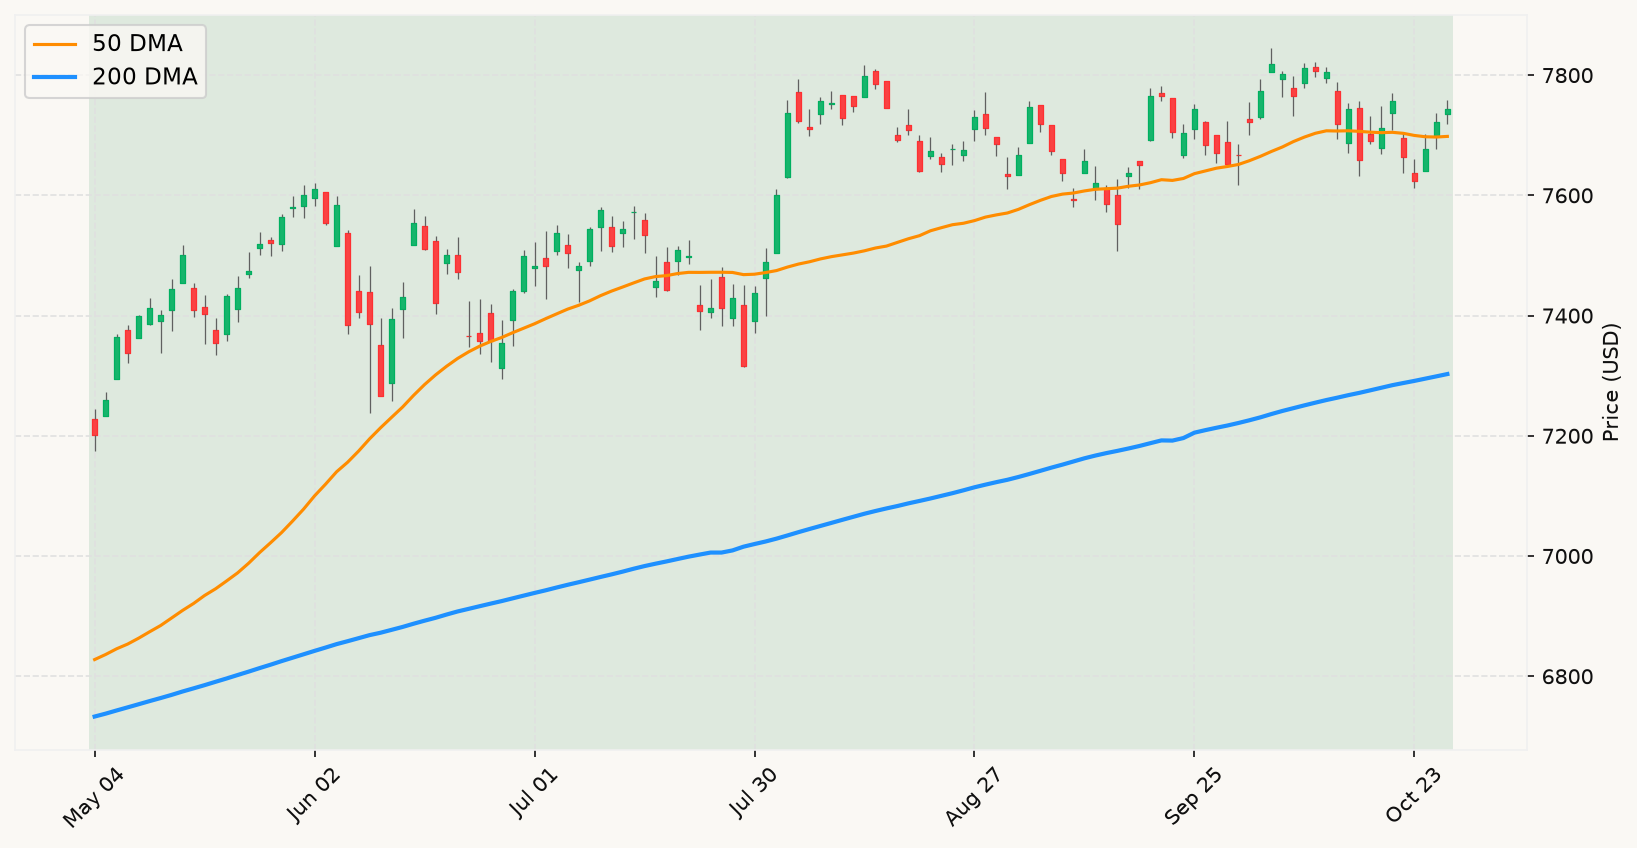
Six Month Chart (SPX)
⊞ Expand
The Ticker Analysis
Bull Trend Intact — Don't Let Alphabet Spook You
The Alphabet miss is the headline grabber this morning, and it's worth separating the signal from the noise carefully. A single quarter's EPS shortfall — even a dramatic one — is exactly the kind of earnings event the historical evidence argues investors should not act on. By the time an earnings miss is news, the information is already being priced in real time. What matters for positioning is not whether Alphabet had a bad quarter, but what the overall market is doing in response to the full sweep of this earnings season. The answer right now is: not much. The S&P 500 is barely negative on the session, and the primary market trend remains firmly bullish. One ugly print from one heavyweight does not constitute a regime change — it's the market's aggregate behavior that tells the real story.
The genuine read from this week's earnings batch is more nuanced than the Alphabet headline suggests. Microsoft's Azure acceleration, Google Cloud's 103% growth, and Oracle's strong free-cash-flow guidance all point to durable enterprise cloud demand. The dispersion within the AI ecosystem is widening — platforms with clear monetization paths are being rewarded, while those still burning capital ahead of visible returns are being punished. That's a healthy market dynamic, not a crisis. The market is doing exactly what it's supposed to do: differentiating. The overall trend in S&P 500 earnings is still one of growth, and breadth in a market where the index is above its primary trend is the expected condition of a functioning bull cycle.
The Fed's hawkish hold deserves more attention than the Alphabet miss in terms of macro implications. Rates held at 3.75%–4.00% with two dissents and December hike odds near 85% means the interest rate environment is tilting incrementally tighter. And yet — the market has absorbed a full year of tightening without breaking the primary trend. The 10-year yield near 5% is elevated but not uncharted territory for an equity bull market, and today's Q3 GDP print of 3.4% annualized confirms that the economy is absorbing this rate environment with resilience. When growth is running hot and the stock market is above its primary trend, the historically correct posture is to remain fully invested. The recession signal checklist — gradual equity deterioration, deteriorating nowcasts, labor market softening — is simply not flashing.
The positioning conclusion is straightforward: the market is in a bull regime, the economic signals are healthy, and the noise-to-signal ratio this week is high. Alphabet's drop is a single-stock event. The Fed's hold was expected. GDP beat estimates. None of this moves the needle on the core diagnostic. The drawdown from the all-time high remains under 1%, the primary market trend is intact, and employment conditions continue to hold up. Investors who are tempted to trim exposure on the back of today's tech turbulence would be making the classic error — mistaking loud headlines for actionable signals. The framework's default posture applies here with full force: stay invested, tune out the noise, and let the market's actual behavior — not this week's earnings drama — tell you when something has changed. MoreLess