The Ticker Analysis
Bull Trend Intact — Tonight's Earnings Are the Real Test
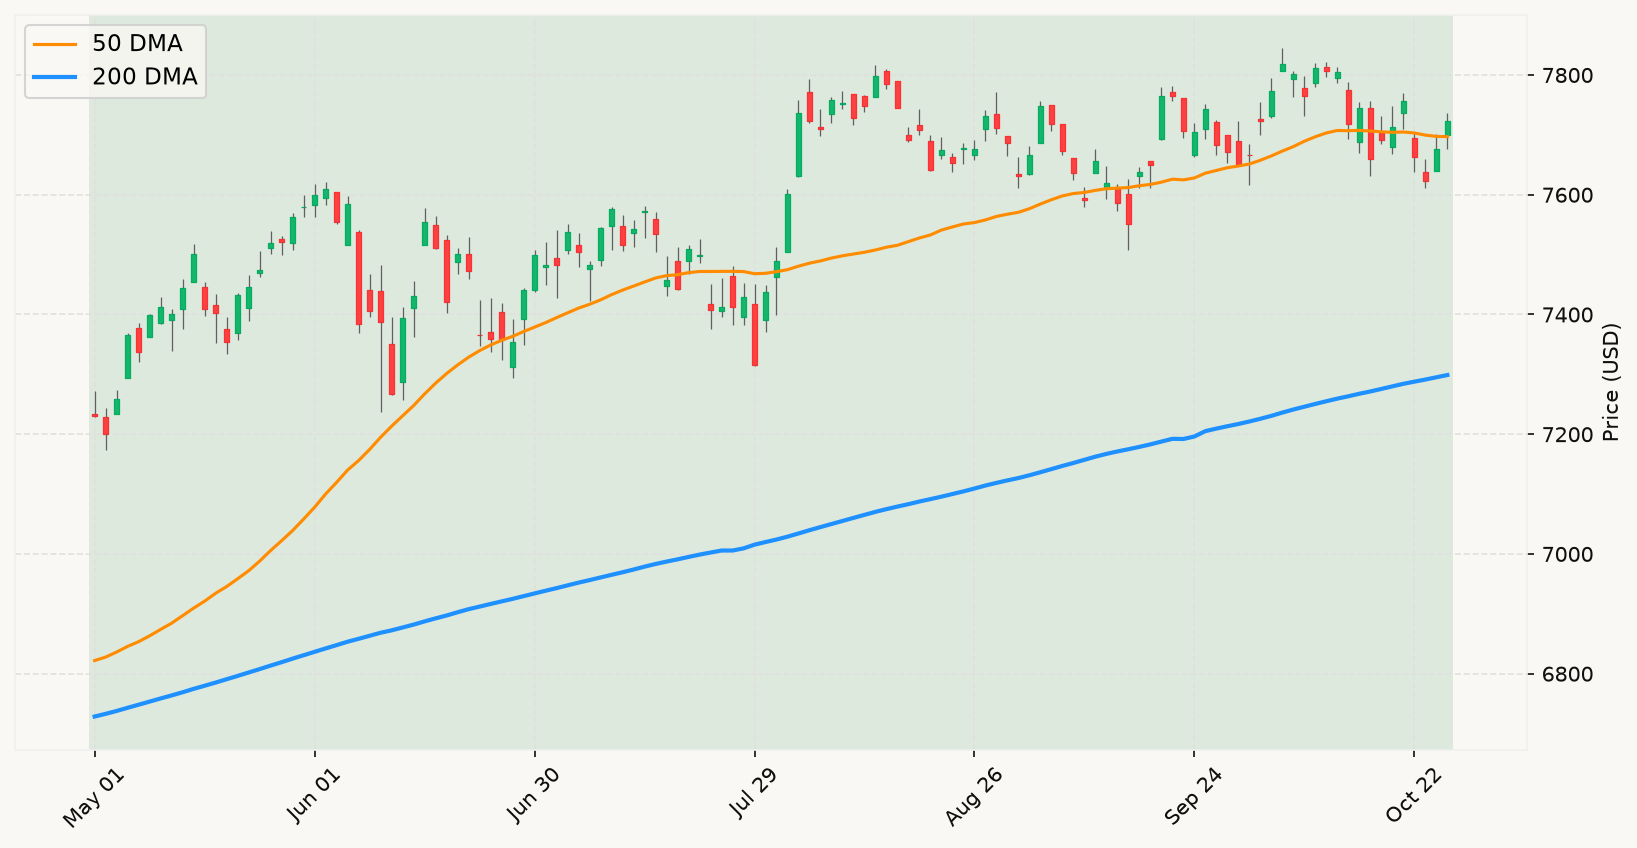
The setup entering today is one of cautious strength, not alarm. The S&P 500 sits comfortably above its primary market trend — the long-term moving average that separates bull regimes from deteriorating ones — and the drawdown from the all-time high is negligible. History is unambiguous on this: markets at or near all-time highs have historically delivered above-average forward returns, not below-average ones. The burden of proof lies with the bears, and right now they don't have the goods. The velocity of this pullback is essentially nonexistent, which eliminates the fast-crash diagnostic entirely. This is a bull market with a minor consolidation, full stop.
The twin macro headwinds — a Fed that may not be finished hiking and oil prices spiking on Middle East risk — are real but well-telegraphed. The interest rate environment has shifted from accommodative to restrictive over the past two years, yet equities have continued to make new highs. That is the market speaking. It has looked at this rate backdrop, priced the geopolitical risks from Iran, and still printed record closes. Dismissing that signal in favor of macro narratives about inflation or oil is exactly the kind of error that costs investors returns. The market aggregates the judgment of every informed participant in real time; it has concluded the bull case outweighs the bear case, and the framework says to respect that verdict until the data says otherwise.
Tonight's Microsoft and Alphabet results are the session's highest-stakes event, and they matter for a specific reason: if AI infrastructure spending is converting to revenue at scale, the earnings foundation for this bull run becomes substantially more durable. The chip rally, the Anthropic IPO buzz, the Oracle-OpenAI tie-up — these aren't noise, they're the earnings cycle telling you where growth is concentrated. Consumer confidence rebounding to 91.7 from 84.2 adds another brick to the wall. Employment conditions remain healthy, monetary policy signals are not yet flashing recession, and the stock market trend is firmly intact. None of the leading economic indicators are converging toward contraction. Without that convergence, defensive positioning is statistically unjustified.
The geopolitical tail risk from Iran is worth monitoring on one specific channel: sustained oil above current levels feeding back into CPI and tipping the Fed toward additional hikes it otherwise wouldn't have taken. That sequence — energy-driven inflation re-acceleration forcing a policy mistake — is the scenario most capable of shifting the macro picture. It is not happening today. It is a condition to watch, not a reason to act. The 80% historical base rate says that episodes like this — where the market is near highs, the economy is growing, and a scary headline generates volatility — resolve in favor of the investor who stayed put. Nothing in today's data flow changes that base rate. Stay invested, watch the earnings tape tonight, and let Chair Warsh's tone on December clarify the rate path before drawing any conclusions about the trajectory ahead. MoreLess