The Ticker
Bull Market
The sun is shining, the crops are growing, and the old bull is still grazing comfortably in the pasture — a little restless from the commotion at the fence, but nowhere near spooked enough to bolt.
Top Story
Anthropic Files for IPO as AI Trade Faces Its Biggest Stress Test Yet
Anthropic, the maker of the Claude AI assistant, made its long-awaited public market debut official Monday, filing its S-1 with the SEC ahead of a planned Nasdaq listing under the ticker ANT. The filing revealed explosive revenue growth but also massive losses and a stark warning that its own technology could pose existential risks to humanity — setting up what may be one of the most consequential and closely watched IPOs in modern market history.
The Anthropic filing lands in the middle of the heaviest earnings week of the season, with roughly a third of the S&P 500 set to report results through Friday. Mega-cap tech names including Amazon, Alphabet, and Microsoft are all on deck, and Wall Street is watching closely for evidence that the enormous capital being plowed into AI infrastructure is translating into real revenue and margin expansion. Meta separately announced plans to raise up to $97.5 billion in equity, doubling down on its own AI ambitions in one of the largest corporate fundraising efforts on record.
The Federal Reserve opens its two-day policy meeting today, with a Wednesday decision widely expected to hold rates steady at 3.75%–4.00%. But the market is already looking past this meeting toward December, with rising inflation pressures — core PCE is expected to accelerate — keeping a potential rate hike squarely in play. The interest rate environment remains a genuine headwind for long-duration growth assets, and investors are recalibrating how much premium to assign to AI-linked equities as the cost of capital stays elevated.
Adding to the complexity, Middle East tensions continue to simmer with Brent crude holding near $115 per barrel despite some diplomatic progress, while fresh labor market data showed private hiring slowing for a second consecutive week. The combination of cooling employment signals, sticky inflation, a pivotal Fed meeting, and a landmark AI IPO makes this one of the more data-rich and sentiment-defining weeks the market has faced all year. MoreLess
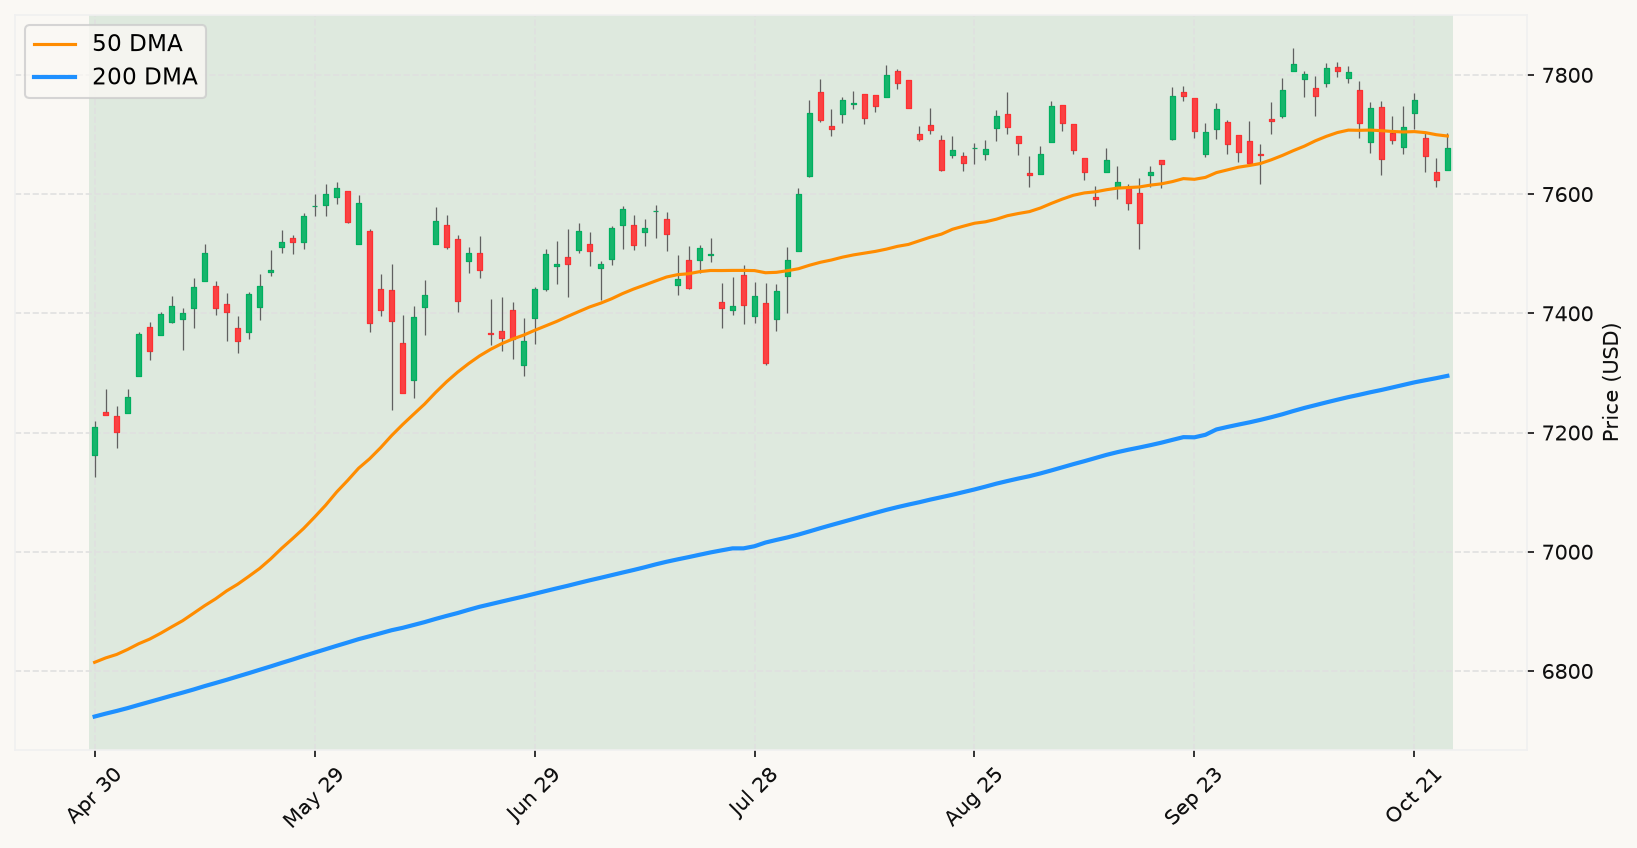
Six Month Chart (SPX)
⊞ Expand
The Ticker Analysis
Noise Is Loud but the Bull Trend Holds
The market's primary trend remains firmly intact — the S&P 500 is comfortably above its long-term stock market trend line, the drawdown from the all-time high is modest and well within normal correction territory, and the 80% historical base rate for self-correcting pullbacks applies with full force here. Nothing in today's news flow changes that structural picture. Anthropic's IPO filing, however dramatic the headlines, is a corporate event — not a recession signal. HSBC cutting equities to neutral is exactly the kind of institutional sentiment shift that the evidence base treats as noise: by the time a major bank publicly announces a tactical reduction, the information is already reflected in prices. The ruling on today's top stories is the same as it almost always is: this is market noise, not a signal that demands repositioning.
The FOMC meeting is the one item on this week's calendar that deserves deliberate attention — not because a hold is surprising, but because the Fed's posture on December matters for the interest rate environment heading into year-end. Monetary policy signals are broadly constructive right now: the 10-year/3-month spread is positive and widening, which is the opposite of the inversion pattern that has historically preceded recessions. A Fed that pauses here while leaving December open is not a threat to the primary bull trend — it is consistent with a late-cycle expansion that remains on track. The market has already priced elevated rates; what it has not priced is a recession, and current leading indicators give no basis for that expectation.
The ADP hiring slowdown and the NY Fed nowcast dipping below the Atlanta Fed's estimate are worth monitoring, but neither clears the bar of a convergent recession signal. Employment conditions remain broadly positive — the Sahm-equivalent threshold has not been triggered, payrolls are slowing but not turning negative, and a two-week deceleration in ADP's pulse survey is well within the noise band of a maturing labor market. The same logic applies to the nowcast divergence: both models are still solidly positive, and the spread between them is well within each model's margin of error. There is no recession signal here. There is only a reminder that the expansion is aging, which is not new information.
The Anthropic IPO and Meta's fundraising blitz are best understood as a real-time liquidity test for the AI trade — and the market's reaction to that test will be more informative than the filings themselves. If mega-cap tech earnings this week confirm that AI capex is converting to revenue at scale, the recent pullback from the all-time high is exactly what corrections look like before they resolve upward. If earnings disappoint, the drawdown could extend — but even then, the framework's prescribed response is patience, not retreat, until and unless the primary stock market trend breaks down on a sustained basis. That has not happened. The posture is fully invested, the burden of proof remains on the bear case, and today's news does not come close to meeting it. MoreLess