The Ticker Analysis
Bull Market Intact — Stay the Course
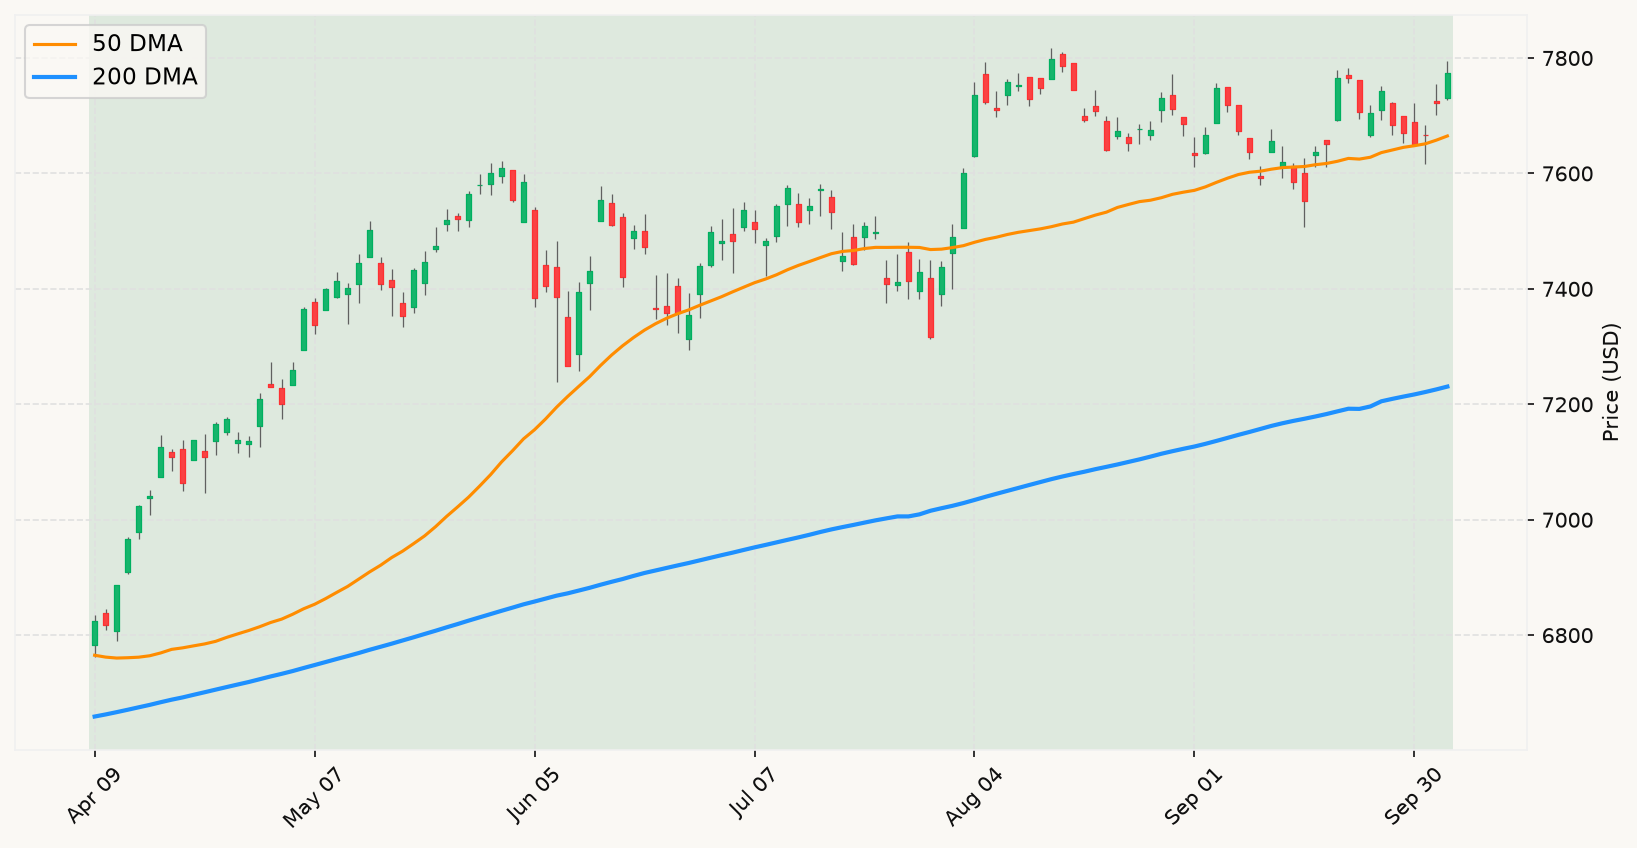
The market's message right now is unambiguous: the primary trend is healthy, the equity tape is constructive, and the burden of proof sits squarely on the bear case. The S&P 500 is trading comfortably above its long-run stock market trend, the Nasdaq just posted a fresh all-time high, and the overall drawdown from the S&P's own peak is a rounding error — well under 1%. Nothing in the price action is sending a warning signal. When the market itself is the most sophisticated real-time aggregator of every known risk, and it's choosing to push technology stocks to records while absorbing 24-year yield highs and a diesel crisis, that's not complacency — that's a verdict. The correct posture is fully invested.
The two macro headwinds dominating headlines — elevated energy costs from the Hormuz disruption and sticky inflation feeding rate-hike speculation — are real, but they're also fully visible. The market has been digesting the Iran conflict, $100+ crude, and rising yields for months, and has ground higher through it all. Aramco's warning that oil inventories may take two years to rebuild is sobering, but it's already priced into every energy model on the Street. Similarly, ISM Services Prices Paid at multi-year highs is not news to institutional investors — it's been the backdrop for weeks. The Nasdaq doesn't set all-time highs in the face of known risks without the collective weight of professional capital deciding those risks are manageable relative to the earnings trajectory. That judgment deserves respect.
The employment picture is the one area worth monitoring carefully — not because it's flashing red, but because the September payroll number (29,000 against an 84,000 estimate) is the kind of sequential softening that, if it persists, could eventually converge with other leading indicators into something more meaningful. For now, the immigration-adjusted labor market trend remains positive, and NY Fed President Williams explicitly signaled no urgency on further tightening. The interest rate environment, meanwhile, has shifted from unambiguously hawkish to genuinely uncertain — the 10-year briefly kissed 5.34%, but pulled back as soon as the payroll miss hit the tape. That whipsaw tells you the bond market is interpreting the data in real time, not pricing in a sustained tightening spiral. No convergence of warning signals is present.
The AI earnings cycle is doing the heavy lifting, and it's doing it convincingly. Nvidia near a $6 trillion market cap, Microsoft grinding higher, and the Nasdaq 100 at records — this is what a bull market in a genuine technology adoption cycle looks like. The right move is to stay invested, avoid the temptation to chase the diesel/yield narrative as a macro exit signal, and let the stock market trend tell you when the regime changes. It hasn't. Until it does, every scary headline is noise by definition — and the historical base rate says acting on noise is far more expensive than ignoring it. MoreLess