The Ticker Analysis
Soft Jobs Report Is a Gift, Not a Warning
The September jobs miss is, at first glance, the kind of number that gives bears something to talk about — but the market's immediate reaction tells you everything you need to know. Futures surged. Bond markets rallied. Rate-hike odds collapsed. That is not how assets behave when participants believe a recession is quietly arriving at the door. The labor market has been grinding at a slow pace for most of 2026, and today's 29,000 print fits within a broader pattern of modest, below-trend job creation that has been in place for the better part of two years. The unemployment rate at 4.2% has drifted up from its lows, but it remains within the narrow band it has occupied since March, well short of the kind of threshold that would signal meaningful deterioration. Employment conditions remain broadly stable — soft, yes, but not cracking.
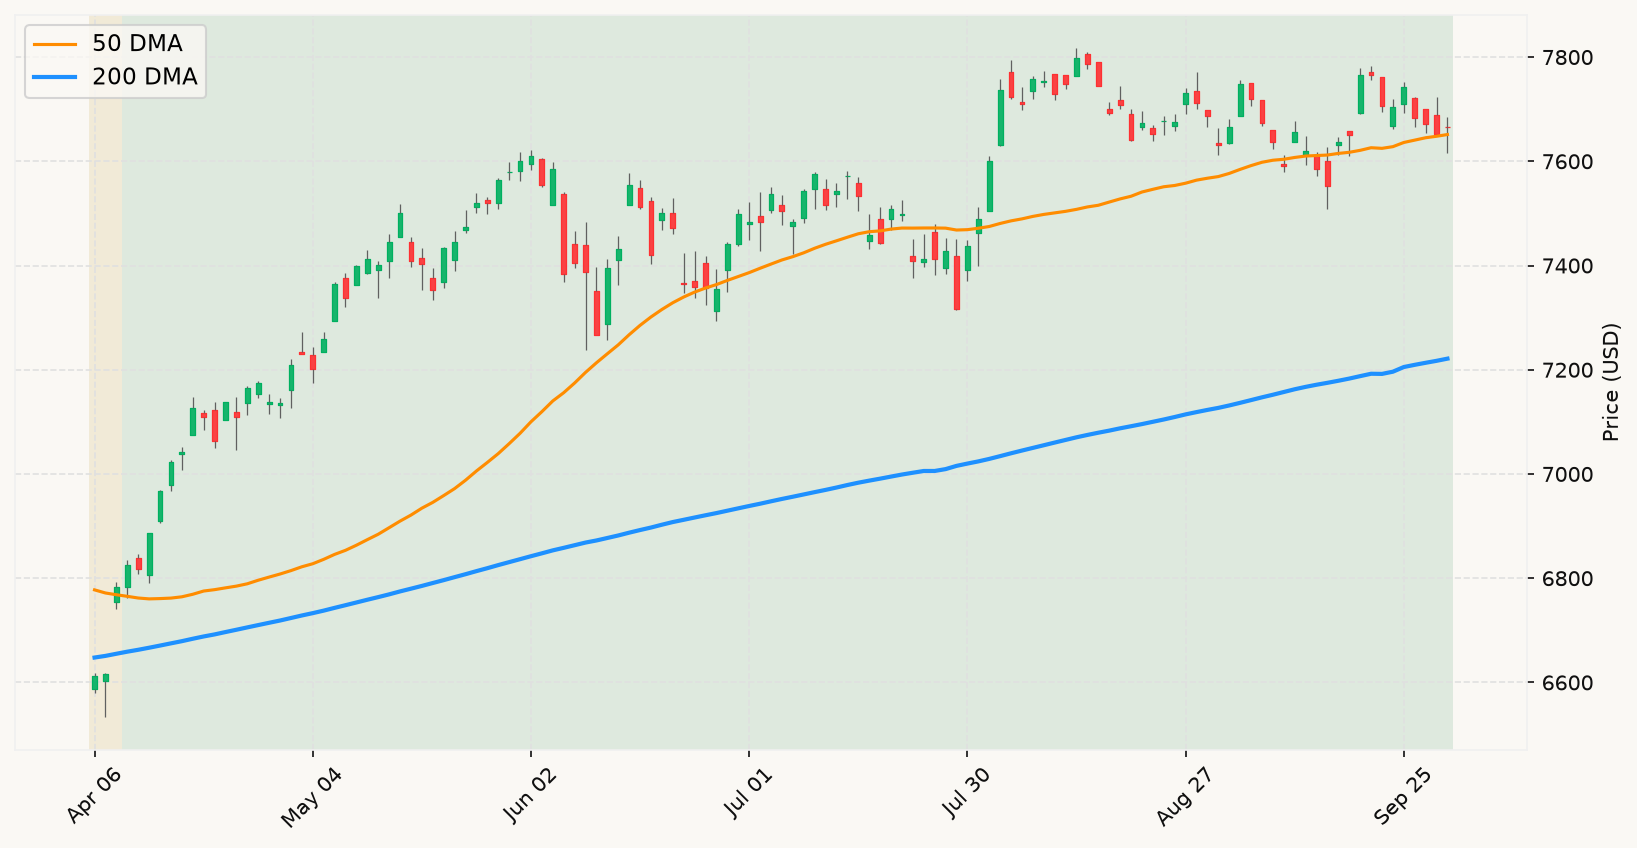
The Accenture result is worth taking seriously as a read on corporate health, even if single-stock earnings are generally noise within the analytical framework that matters here. What is signal is what it implies about the broader earnings season: a mega-cap consulting firm, facing existential fears about AI displacement, just posted its best bookings quarter on record and raised guidance. That is not consistent with a corporate sector that is pulling in its horns. Add in the Anthropic IPO narrative — a potential $2 trillion listing on the horizon — and you have a market that is actively pricing in a thriving AI-driven economy, not a recessionary one. The primary market trend is firmly above its long-term average, the stock market itself remains the most important signal available, and right now it is not confirming any recessionary hypothesis.
The oil situation from the Iran conflict is the one genuine macro wildcard worth watching — not because it changes the immediate signal, but because it represents the kind of persistent supply shock that can feed into inflation and force the Fed's hand in ways that slower-moving indicators don't capture instantly. A central bank that feels compelled to resume hiking into a softening labor market would be a qualitatively different environment than what currently exists. That said, the interest rate environment, while historically elevated, is sending a bullish message today: the spread between long and short rates is positive and widening, which is the opposite of the monetary policy configuration that has historically preceded recessions. This is not an environment that calls for defensive repositioning.
The bottom line from every angle the framework provides is the same: the stock market is above its primary trend, the recession checklist has no confirmed boxes, employment conditions are stable rather than deteriorating, the interest rate environment is constructive, and growth nowcasts are solidly positive. The base rate says that 80% of market pullbacks — even 10%+ ones — resolve without becoming prolonged bears, and the current 1.7% drawdown from the all-time high doesn't even register in that dataset. The appropriate posture is fully invested, with a watchful eye on oil's inflation pass-through and any sign that the labor market softness accelerates rather than stabilizes. Today's jobs miss, paradoxically, is a mild positive: it takes the most plausible near-term risk — a Fed hike that chokes demand — largely off the table for October. MoreLess