The Ticker Analysis
Bull Trend Intact — Stay the Course
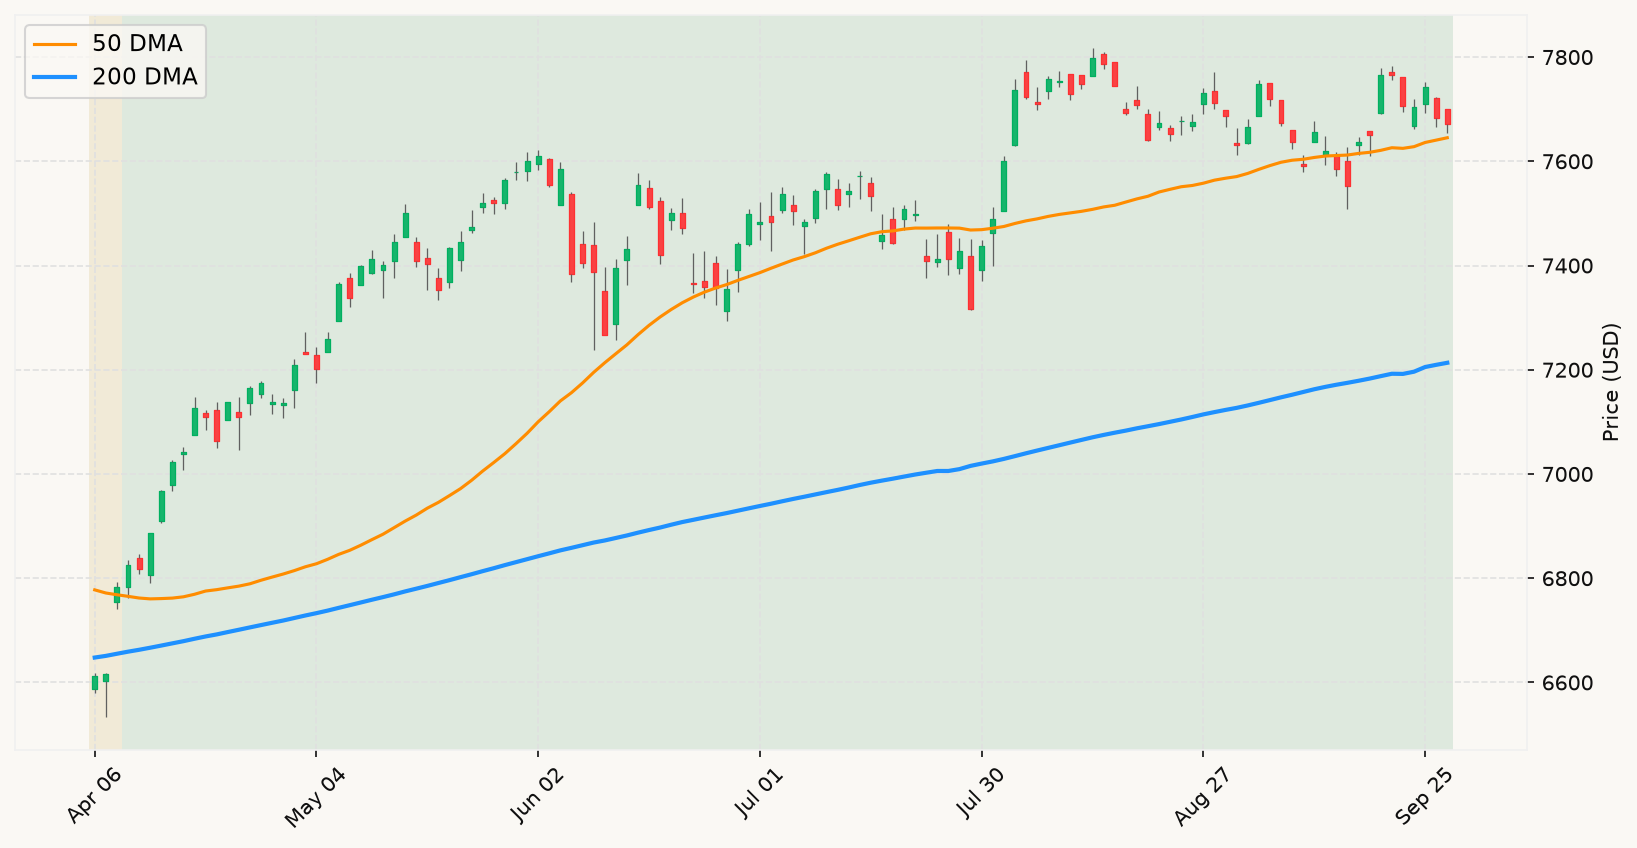
The signal that matters most this morning is the one easiest to overlook amid the White House spectacle: the S&P 500 is sitting comfortably above its primary market trend, just 1.6% off an all-time high set less than two months ago. That's the dominant fact in the framework. Everything else — the AI accord drama, the Micron earnings suspense, the hand-wringing over consumer confidence — runs through that filter first. A market that is this close to a record high, with a still-positive primary trend, is unambiguously in bull market territory. There is no diagnostic work to do on the bear case because the bear case hasn't shown up in the only place that counts: price action.
The White House AI summit and the resulting "accord" are pure noise from a positioning standpoint. Not because AI doesn't matter — clearly it does, enormously, as Micron's pending blowout quarter and the relentless demand for HBM memory will confirm — but because by the time a summit is televised, signed, and analyzed on every financial network, the market has already priced whatever signal it contains. The accord is a political event dressed in market clothing. What matters is whether AI-driven capital expenditure continues to flow at a rate that sustains corporate earnings growth. Micron's Q4 guidance tonight will do far more to answer that question than any document signed in the East Room.
The PCE print coming in cooler than expected is modestly constructive for rate-sensitive positioning, but the interest rate environment here demands respect. Treasury yields at multi-decade highs are a genuine constraint — they raise the discount rate on future earnings, they compete with equities for capital, and they are starting to show up in softening consumer confidence and declining job openings. None of this is recession confirmation. Labor market signals remain broadly healthy — employment conditions have not deteriorated in any way that would trigger the second leg of a recession diagnostic. But the combination of elevated yields, compressed consumer sentiment, and a Fed that just hiked and is signaling more creates real conditions for a grinding, choppy tape rather than a clean breakout to new highs.
The correct posture here is fully invested, with clear eyes. The primary market trend is bullish, the labor market is not breaking, and the velocity of any decline so far is nowhere near the threshold that would demand defensive action. The 80% base rate — that the overwhelming majority of corrections resolve without becoming prolonged bears — has no reason to be overridden. Micron's earnings tonight are worth watching as a live read on AI infrastructure demand, but they are a data point within the bull case, not an on/off switch for overall equity exposure. Stay invested, stay diversified in broad index exposure, and resist the temptation to confuse a noisy, high-yield, headline-heavy environment with one that is actually sending a sell signal. It is not. MoreLess