The Ticker Analysis
Bull Trend Intact — Stay the Course
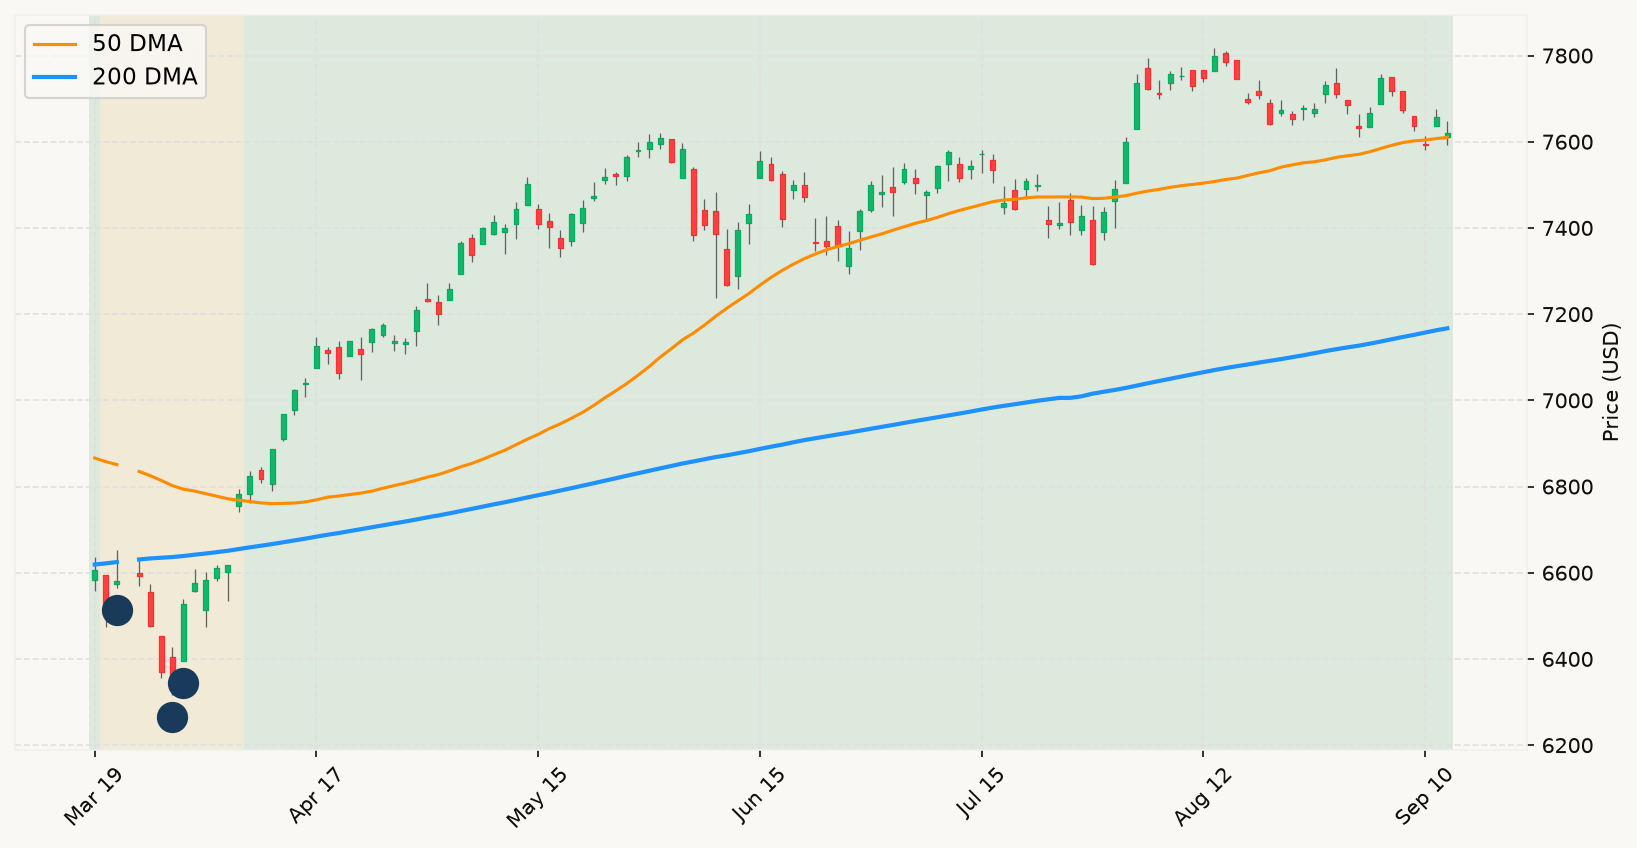
The AI slowdown call is the headline du jour, but through a disciplined lens, it registers as noise masquerading as signal. The market is solidly above its primary trend line — a clean bull confirmation — and the current drawdown from the all-time high is a modest 2.3%, well within the statistical noise range that characterizes normal intra-year volatility. The base rate here is unambiguous: declines of this magnitude, occurring with this velocity profile and within this time window, have resolved themselves without becoming prolonged bear episodes in the overwhelming majority of historical cases. One essay from a CEO, however consequential to the AI narrative, does not change any of the underlying trend diagnostics.
The more interesting read on the AI news is what the market itself is telling us about it. Chip stocks took a sharp hit, cybersecurity rallied, and the broad index closed down less than half a percent — that is not the market pricing in a structural collapse of AI spending. That is sector rotation within an intact bull regime. If the AI slowdown call were truly signaling the end of the capital expenditure supercycle, you would expect the market to begin the slow, grinding deterioration that historically precedes recessionary bears. Instead, the price action looks more like a sentiment-driven shakeout in a concentrated theme, which is exactly the kind of episode the historical record says to sit through. The broad employment picture remains healthy, real-time growth indicators are pointing solidly positive, and the interest rate environment — while tightening — is not inverted in a way that has historically preceded recessions with reliability.
The Saudi pipeline shutdown and oil spike above $107 deserve a more careful look, not because energy price spikes are reliable recession predictors on their own, but because of the inflationary feedback loop they create heading into a Fed meeting already tilted toward hiking. A sustained oil shock that keeps CPI elevated longer than expected could push the Fed further than the market has currently priced — and it is precisely this kind of slow-building macro headwind, not a dramatic one-day event, that warrants monitoring against leading economic indicators. That said, the stock market trend remains the most important single input, and it has not deteriorated in a way that demands defensive action. Vigilance, yes. Repositioning, no — not with the current drawdown this shallow and the time window this short.
The Fed hike itself is a known event — markets have been pricing it in for weeks. Known events that arrive on schedule rarely create the kind of sustained trend breaks that matter within a disciplined framework. What matters is the trajectory after the announcement: does the market hold its primary trend, or does it begin the kind of grinding erosion that would warrant escalating concern? Right now the answer is clearly the former. The 80% base rate — that the vast majority of pullbacks of this magnitude resolve without becoming prolonged bears — argues strongly for staying fully invested. The burden of proof remains on the bear case, and that case simply has not made itself yet. Both growth nowcasts are running comfortably in positive territory, labor market signals remain constructive, and the stock market trend is intact. That is not a setup that calls for defense — it is a setup that calls for patience and discipline. MoreLess